Opportunity to participate as a passive minority shareholder, alongside a highly experienced U.S. sponsor and best-in-class Irish hotel operator, in the Eccles Hotel — one of Ireland's oldest coastal hotels.
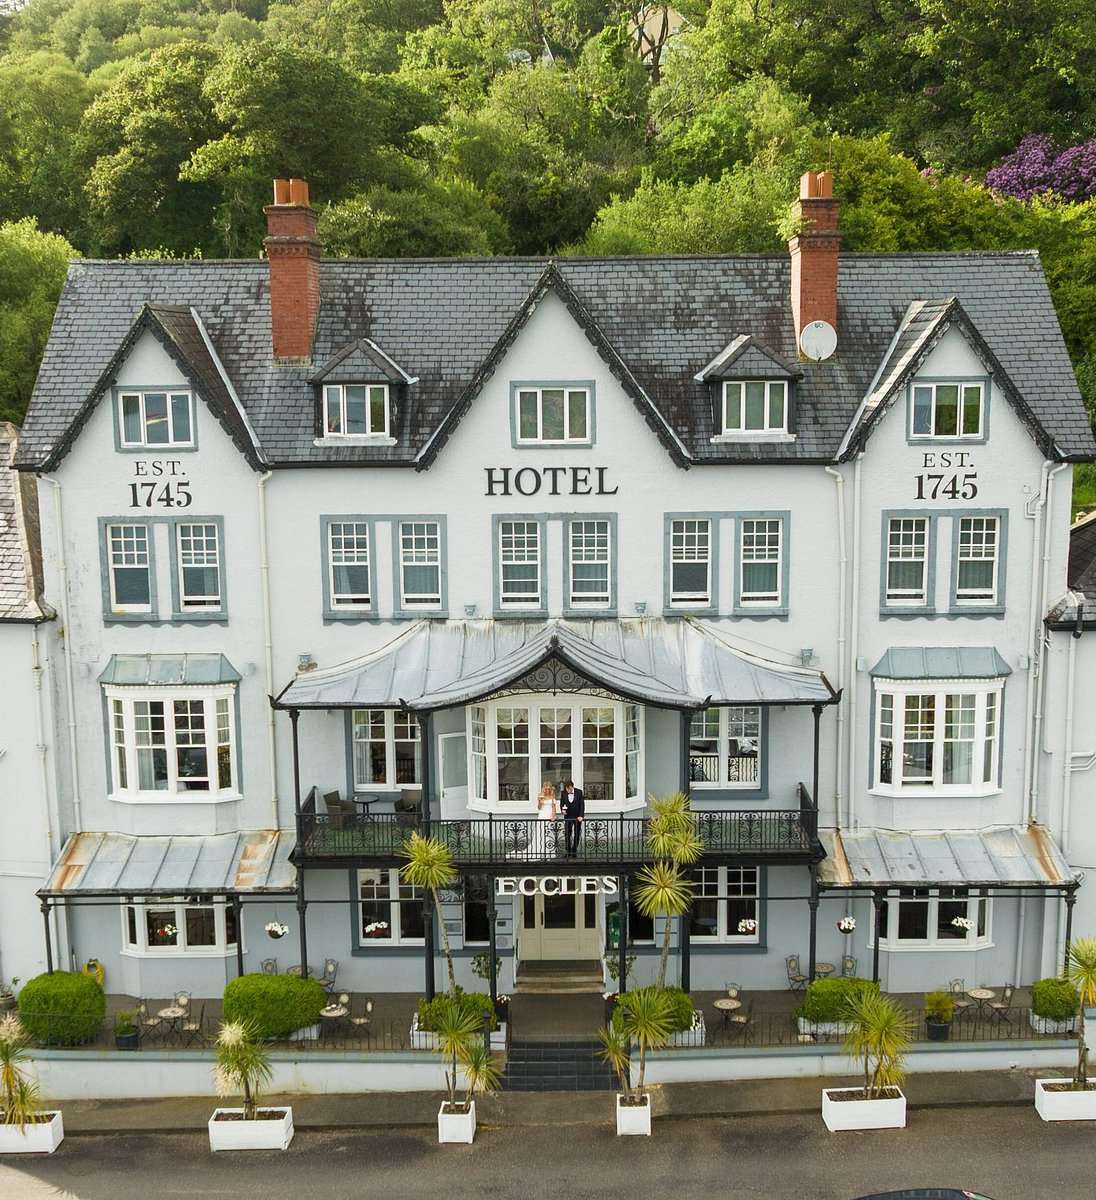
The Eccles Hotel & Spa is a 60-key landmark on the shore of Bantry Bay, West Cork — trading at €3.1m revenue and 41.4% occupancy against a competitive set at 66.6%, already at rate parity (€150 vs €149 ADR). The gap is product condition and demand capture. Entry at €3.3m, €7.8m all-in (€129k per key), against a Year-5 exit underwritten at €179k per key.
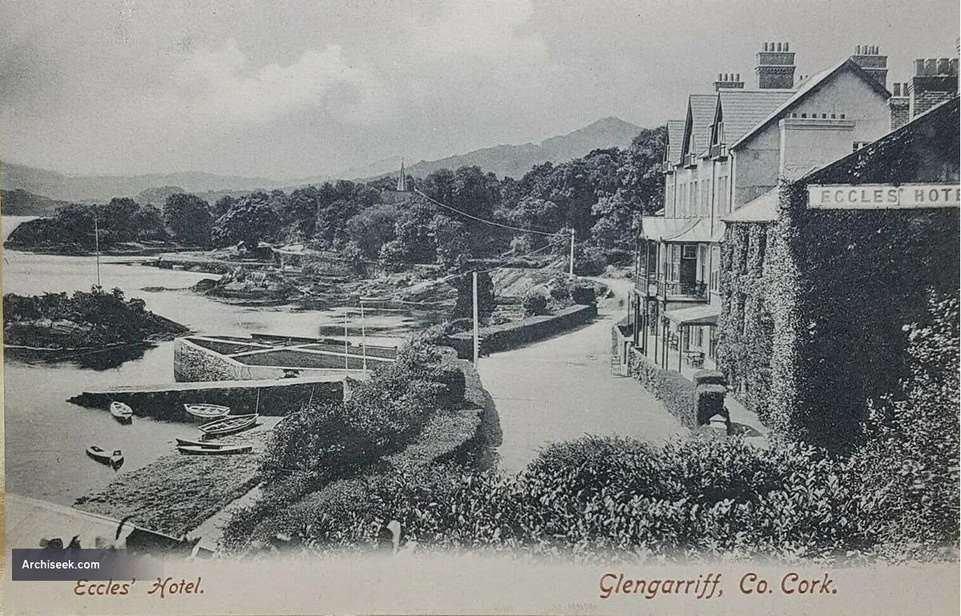
Established 1745. Thackeray boarded here; Shaw wrote here in 1910–11; Yeats was a regular — the Presidential Suite carries his name. A protected trading heritage asset on the waterfront, acquired well below replacement cost.
TTM June 2026: 41.4% occupancy at €150 ADR against a CoStar competitive set at 66.6% and €149. The plan takes occupancy to 56% — still below the set — and ADR to €189 on the renovated product, lifting RevPAR from €62 to €106 against €99 for the set today.
BPM & Company Inc (sponsor, est. 2002 — hospitality investment and asset management, principal in every deal) with Windward Hospitality Group (Dublin-based hotel management, Ireland & UK repositioning track record) under a third-party management structure.


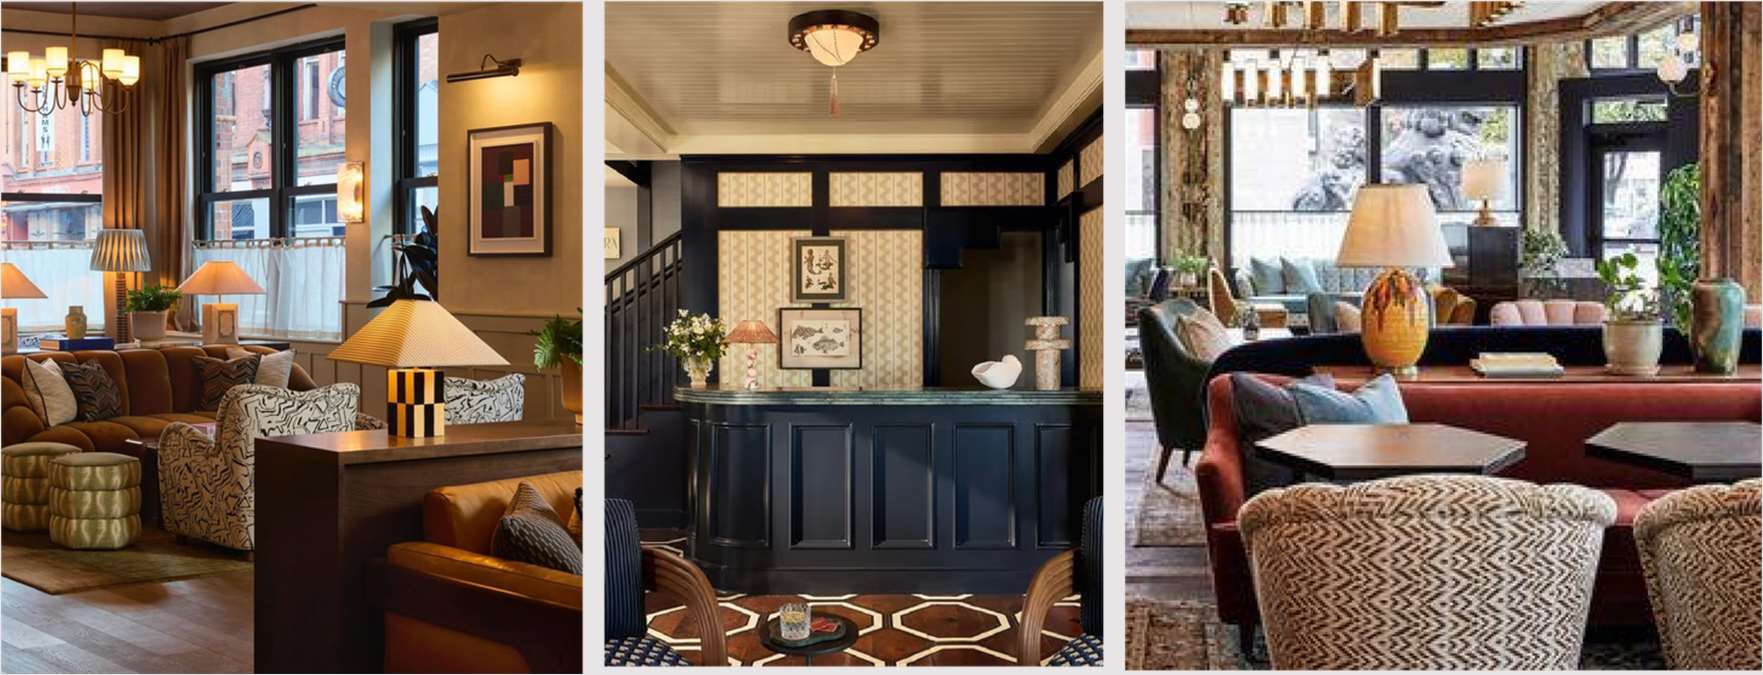
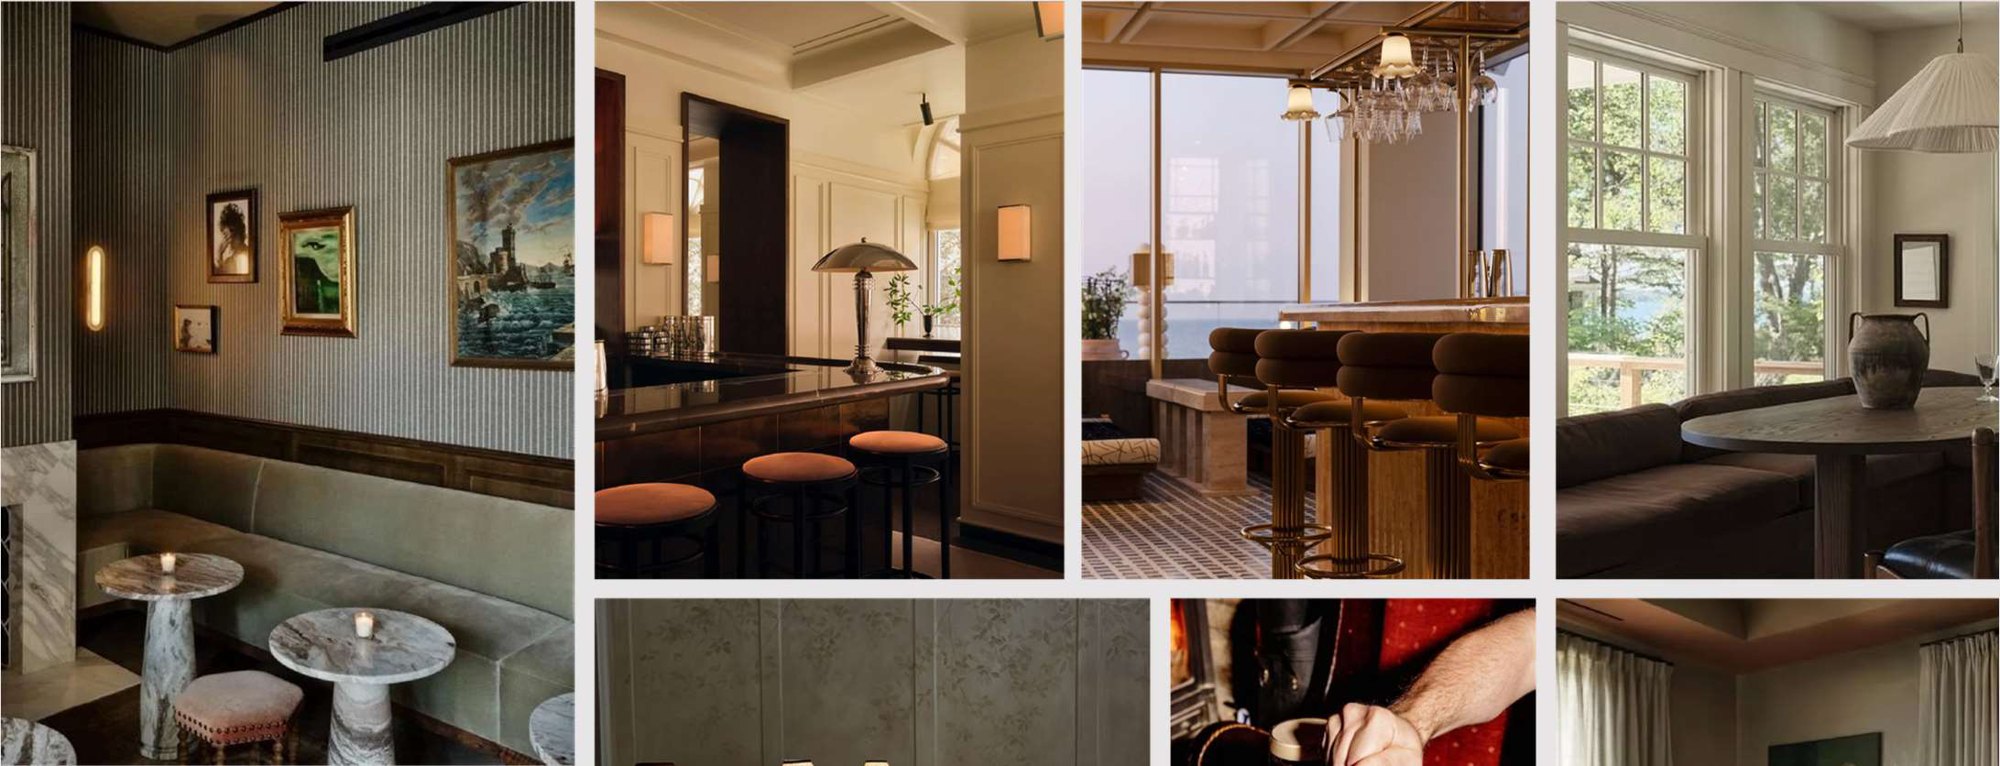
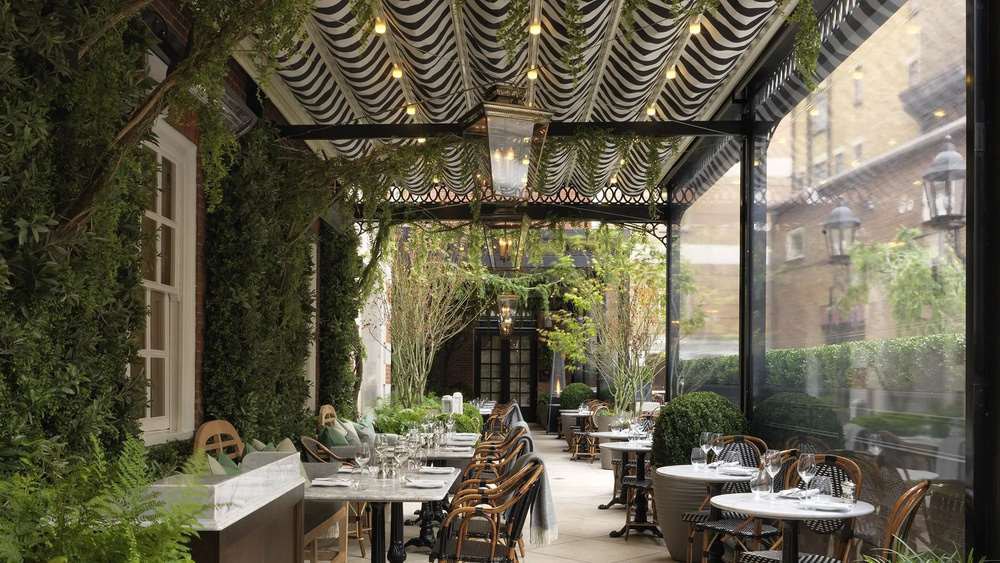
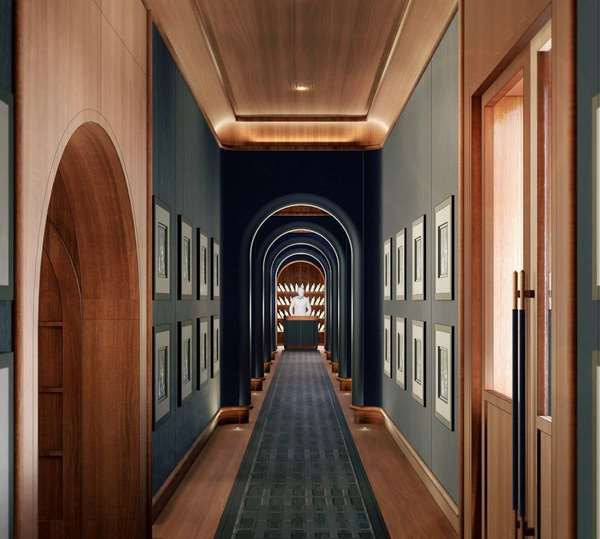
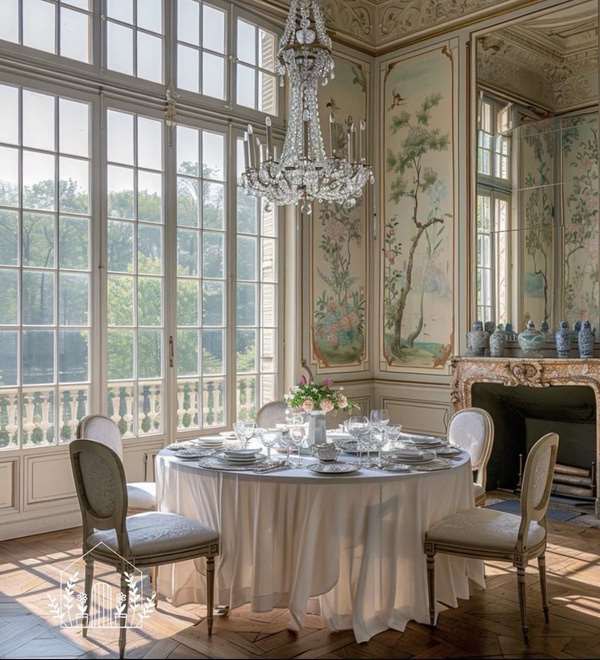
GW Design (architecture + interiors) has completed the initial design direction: a facade returned to its Victorian elegance, a re-sequenced arrival, a 71-cover restaurant and cocktail bar over the water, conservatory, ballroom, spa, and all 60 keys re-cased — heritage elements preserved throughout, phased around a short winter closure (7 January – 1 March 2027).


| Repositioning scope | € |
|---|---|
| Guestrooms & suites — case goods, soft goods, flooring, two DAC rooms | |
| Public areas — reception, restaurant, bar, banquet suite, corridors | |
| Exterior, facade & landscaping | |
| Physical & mechanical — fire/life safety, windows, boiler, roof, energy | |
| Design, project management, freight & contingency | |
| Total repositioning capex — €54.6k per key | 3,275,060 |
Total per BPM & Company sponsor proforma (v 5.5, 9 September 2026); phased over Year 1.
US hospitality investment and asset management firm, established 2002. Value-based, cashflow-oriented hotel acquisitions in secondary markets since 2012; acts as principal / managing member in every investment. The majority of the equity is committed by passive US investors alongside the sponsor.
bpmcoinc.comDublin-based hotel investment and management platform operating across Ireland and the UK for private equity, family office and institutional owners — with repositioning credentials including Harvey's Point and The Fleet Hotel. The Eccles will trade under a third-party management agreement for the full hold.
winmgt.ieA fully capitalised €7.8m transaction: €3.1m of equity, conservative leverage at entry, and a debt resize on completion of works. Returns are driven by trading recovery and repositioning — not by exit-yield compression.
Acquisition at €3.3m with senior debt at 81% of purchase price. Windward assumes management at completion.
€3.3m phased capex programme to upper-upscale standard; facility resizes to €4.7m on completion of works, releasing capex funding.
Rate-led stabilisation to €5.2m revenue and €1.1m EBITDA by Year 5 — ADR to €189, RevPAR to €106.
Sale at stabilisation, underwritten at an 8.5% residual cap rate — €10.8m gross, €179k per key.
| Sources & uses | € | Per key |
|---|---|---|
| Uses | ||
| Purchase price | 3,300,000 | 55,000 |
| Closing costs | 521,220 | 8,687 |
| Reserves & working capital | 668,077 | 11,135 |
| Repositioning capex | 3,275,060 | 54,584 |
| Total uses | 7,764,358 | 129,406 |
| Sources | ||
| Senior debt at acquisition — 81% of purchase price | 2,673,000 | 44,550 |
| Facility upsize on completion of works | 2,000,000 | 33,333 |
| Investor equity | 3,091,358 | 51,523 |
| Total sources | 7,764,358 | 129,406 |
Facility resizes to €4.7m at 6.6% all-in following completion of works (entry coupon 7.26%). Debt service cover reaches 2.9× by Year 3.
| Five-year plan | Yr 1 | Yr 2 | Yr 3 | Yr 4 | Yr 5 |
|---|---|---|---|---|---|
| Occupancy | 49.9% | 54.8% | 56.0% | 56.0% | 56.0% |
| ADR | €160 | €173 | €178 | €184 | €189 |
| RevPAR | €80 | €95 | €100 | €103 | €106 |
| Total revenue (€m) | 3.47 | 4.27 | 4.86 | 5.00 | 5.15 |
| EBITDA (€k) | 238 | 714 | 1,080 | 1,088 | 1,120 |
| NOI after FF&E reserve (€k) | 169 | 586 | 886 | 888 | 914 |
Sponsor underwriting vs TTM June 2026 actuals of €3.09m revenue / €274k EBITDA. Year 1 reflects the renovation closure (7 Jan – 1 Mar 2027) and a 59-key inventory. Year 5 RevPAR of €106 compares with €99 for the CoStar competitive set today.
Four years of trading average €3.1m of revenue (YE 2022 – YE 2025) on today's unrenovated product. Against the CoStar competitive set the Eccles already matches on rate (€150 vs €149 ADR, TTM June 2026) but captures only 62% of set demand (41.4% vs 66.6% occupancy). The repositioning capex behind the recovery is set out in §2.
| Summary P&L — €'000 unless stated | YE 2022 | YE 2023 | YE 2024 | YE 2025 | TTM Jun 26 |
|---|---|---|---|---|---|
| Key indicators | |||||
| Occupancy | 46.3% | 44.8% | 43.4% | 44.2% | 41.4% |
| ADR | €132 | €150 | €151 | €148 | €150 |
| RevPAR | €61 | €67 | €65 | €65 | €62 |
| Profit & loss | |||||
| Total revenue | 3,064 | 3,206 | 3,033 | 3,103 | 3,092 |
| Departmental expenses | (1,826) | (1,856) | (1,968) | (1,870) | (1,927) |
| Gross operating income | 1,238 | 1,350 | 1,065 | 1,232 | 1,165 |
| Undistributed expenses & management fees | (794) | (898) | (886) | (805) | (792) |
| Gross operating profit | 444 | 452 | 179 | 428 | 372 |
| Fixed expenses | (73) | (91) | (100) | (105) | (98) |
| EBITDA | 372 | 362 | 79 | 323 | 274 |
| FF&E reserve | (123) | (128) | (121) | (124) | (124) |
| Net cash flow | 249 | 233 | (42) | 199 | 151 |
Historic trading per vendor accounts as compiled in the sponsor proforma ("Eccles Hotel IRE (9-9-26) Proforma v 5.5", BPM & Company); trailing twelve months to June 2026.
Competitive set per CoStar as compiled in the sponsor proforma, trailing twelve months to June 2026. Sponsor underwriting reaches €189 ADR by Year 5.
The underwriting model, GW Design presentation and trading history are available under NDA.
Grand Canal Capital Partners | Confidential. This teaser is for discussion purposes only and does not constitute an offer, invitation or recommendation to invest. Financial figures are projections from the sponsor's underwriting model ("Eccles Hotel IRE (9-9-26) Proforma v 5.5", BPM & Company) and are not guaranteed; historical trading per vendor information. Project IRR is deal-level and pre-promote; limited-member returns are after the sponsor promote under the LLC Agreement waterfall. Returns and shareholding are pre-tax estimates subject to final structuring and documentation. Design imagery per GW Design presentation, 23 July 2026 — indicative look & feel, not final schemes. Aerial photography © Eccles Hotel.